Statutory Analysis
Doctor & Clinic Billing: OPD Consultation Receipts & Entry 74 GST Exemption Explained
GST Exemption on Healthcare Services: Understanding Entry 74
Under Notification No. 12/2017-Central Tax (Rate) dated 28th June 2017 (Entry 74), health care services provided by a clinical establishment, an authorized medical practitioner, or paramedics are completely EXEMPT from Goods and Services Tax (GST).
What Qualifies as Exempt Healthcare Service?
Services for diagnosis or treatment or care for illness, injury, deformity, abnormality or pregnancy in any recognized system of medicines in India (Allopathy, Ayurveda, Homeopathy, Unani, Yoga, and Siddha) qualify for exemption. However, cosmetic surgery or hair transplant undertaken without medical necessity does NOT qualify for exemption.
Required Information on Doctor OPD Consultation Slips
Even though consultation services are exempt from GST, doctors must issue official payment receipts for patient reimbursement, Mediclaim claims, and income tax Section 80D documentation. The receipt must display:
- Doctor's Full Name & Qualifications: E.g., MBBS, MD (Medicine), DM (Cardiology).
- State Medical Council or NMC Registration Number: Critical for verifying registered practitioner status.
- Patient Demographic Details: Name, Age, Gender, and OPD Slip Reference.
- Statutory Exemption Citation: Stating "Healthcare service exempt from GST under Notification No. 12/2017-Central Tax (Rate)".
Separating Clinic OPD Fees from Pharmacy Sales
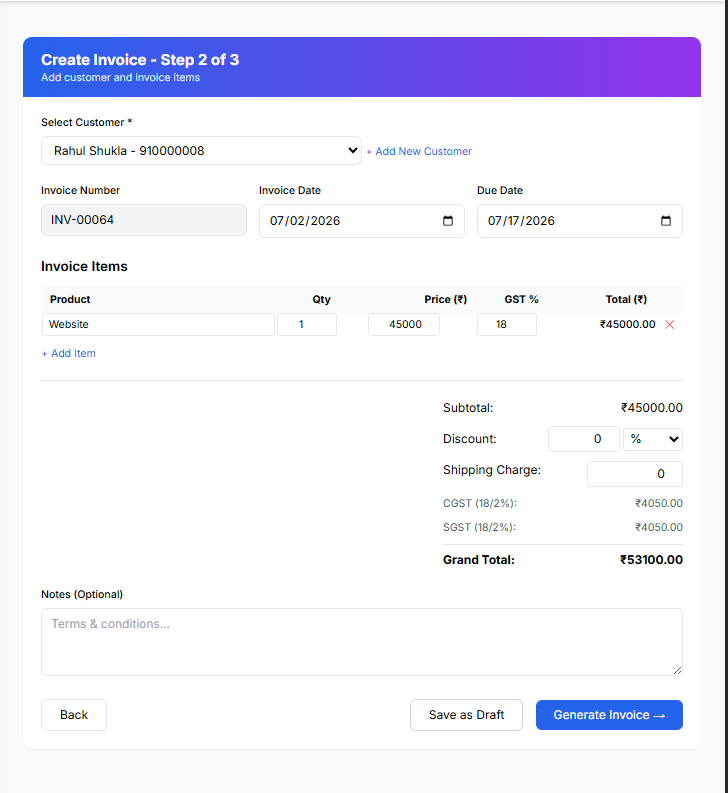
A common trap during GST audits is mixing pharmacy revenue with consultation revenue. If medicines are dispensed as part of outpatient treatment with separate pricing, the medicines attract GST (5% or 12%), while the consultation fee remains 0%. Using BillBr's specialized Clinic Invoicing Tool ensures proper tax segregation.
Akshay Tamrakar
akshay.tamrakar@gmail.com